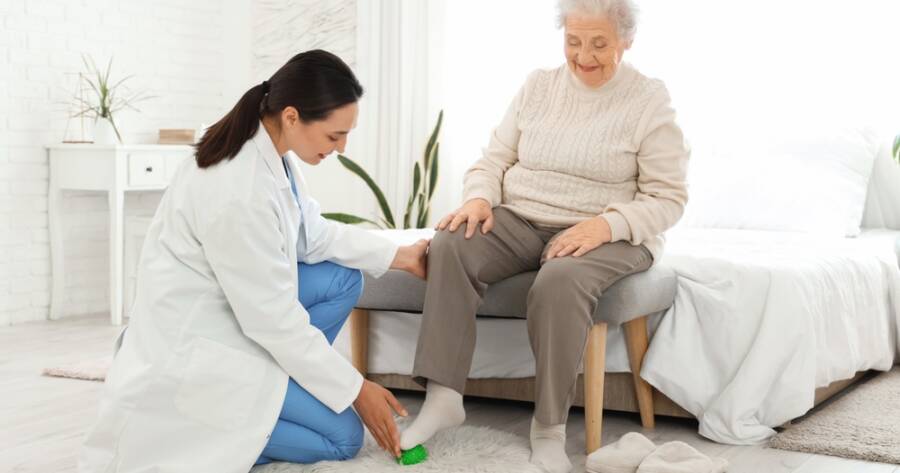
Foot problems can have a major effect on comfort, balance, mobility, and independence later in life, making regular care especially important for many older adults. Medicare may help pay for certain foot exams and treatments, but coverage depends heavily on the reason care is needed. Understanding where Medicare draws the line can help seniors avoid unexpected expenses.
What Medicare Generally Does and Does Not Cover for Foot Care
Medicare Part B provides coverage for foot-related services when those services are deemed medically necessary. This means a podiatrist visit tied to a specific foot injury, structural deformity, or diagnosed disease may qualify for coverage. Conditions such as hammer toe, bunion deformities, and heel spurs are examples of issues that can meet this threshold (source).
However, Medicare draws a clear line when it comes to routine foot maintenance. Services like trimming or clipping nails, removing or cutting corns and calluses, and general hygienic foot care such as soaking or cleaning are not typically covered (source). Seniors who receive these routine services without meeting a medical necessity exception will generally be responsible for the full cost out of pocket.
Diabetes and Foot Care: A Special Category of Coverage
For seniors living with diabetes, Medicare extends more specific foot care benefits under Part B. Diabetic peripheral neuropathy, a condition involving nerve damage in the lower legs that increases the risk of serious complications including limb loss, can make a beneficiary eligible for covered foot exams and treatment (source).
To qualify for this coverage, a beneficiary must have both diabetic peripheral neuropathy and a documented loss of protective sensation. When these criteria are satisfied, Medicare covers foot care visits on a recurring basis every six months, provided the beneficiary has not seen a foot care professional for any unrelated reason during that period (source).
This six-month interval is important to understand. If a senior with diabetes visits a foot care provider for a separate issue between covered appointments, their next qualifying exam may be affected. Keeping track of all foot-related appointments and their documented reasons can help beneficiaries maintain their eligibility for these covered visits.
Systemic Conditions That May Unlock Foot Care Coverage
Beyond diabetes, certain systemic conditions can also shift otherwise excluded foot care services into covered territory. Medicare recognizes that metabolic, neurological, and peripheral vascular diseases can create circumstances where routine-seeming foot care becomes medically necessary (source).
When a systemic condition is the basis for a foot care claim, proper documentation and billing codes become essential. Providers are required to attach specific billing modifiers, designated as Q7, Q8, or Q9, to indicate the nature and degree of the systemic condition present (source). Without these modifiers attached to the claim, Medicare will not process the service as a covered benefit.
Covered exceptions to routine foot care are generally considered medically necessary once every 60 days. Any services performed more frequently than this interval are at risk of being denied as not reasonable and necessary (source). Both beneficiaries and their providers benefit from understanding these frequency limitations before scheduling appointments.
Understanding Cost-Sharing for Covered Foot Care Services
When Medicare does approve foot care as medically necessary, the cost-sharing structure follows the standard Part B model. After satisfying the annual Part B deductible, a beneficiary pays 20 percent of the Medicare-approved amount for any covered services received from a physician or qualified health care provider (source).
For services that fall outside covered categories, the full cost responsibility shifts to the beneficiary. This distinction between covered and non-covered services is one reason why seniors benefit from clarifying, before any appointment, whether their provider accepts Medicare assignment and whether the specific service being performed qualifies under their plan.
Supplemental insurance, often called Medigap, may help offset some of the out-of-pocket costs that remain after Medicare pays its portion. Seniors enrolled in Medicare Advantage plans should review their individual plan documents, as benefits can vary from one plan to another and may differ from Original Medicare coverage.
Why You Should Learn More About Medicare Foot Care Benefits Today
Foot care coverage under Medicare is more nuanced than many seniors realize. The distinction between routine services and medically necessary treatment determines whether Medicare contributes to the cost or whether the beneficiary absorbs it entirely. Conditions like diabetes, peripheral neuropathy, and certain vascular diseases can shift that equation meaningfully.
Staying informed about eligibility requirements, frequency limitations, and proper documentation ensures seniors can access the foot care benefits available to them without facing avoidable out-of-pocket expenses. Speaking with a licensed Medicare counselor or a qualified podiatrist who accepts Medicare assignment can help beneficiaries better understand how these rules apply to their specific health situation.